SUV Financing in Bahrain: A Plain-Language Guide to Buying Your JAC on Instalments
Most new SUVs on Bahrain’s roads were bought with a loan, not a lump sum. Understanding SUV financing in Bahrain before you visit a showroom puts you in a stronger position to negotiate and helps you choose a payment you will still be comfortable with in year four. This guide from JAC Motors Bahrain, part of Khalil Kanoo Motors W.L.L., explains how it works in plain language.
How SUV financing works in Bahrain
A car loan in Bahrain is normally arranged through a local bank or finance company, often directly from the dealership. The lender pays the dealer, you repay the lender in fixed monthly instalments, and the vehicle is registered with the lender as a mortgagee until the final payment is made. Both conventional and Islamic (Murabaha or Ijara) structures are widely available.
The five numbers that set your monthly payment
1. Vehicle price
The starting point. Promotions and model-year offers from the dealer reduce this directly, so always ask what is current before you calculate anything.
2. Down payment
Lenders in Bahrain typically ask for a down payment of around 10 to 20 percent of the vehicle price, though some promotions offer lower entry amounts for salaried applicants. A larger deposit lowers both the monthly payment and the total interest paid.
3. Tenure
Car loans usually run from one to seven years. A longer tenure means a smaller monthly figure but more interest overall. A common rule of thumb is to match the tenure to how long you realistically expect to keep the car.
4. Rate
Rates are usually quoted as a flat annual rate. Ask for the total amount payable as well as the monthly figure so you can compare offers like for like.
5. Insurance and fees
Comprehensive insurance is required for financed vehicles and is often included in the first year. Check for processing fees, early settlement charges and whether registration is bundled.
What lenders will ask for
- CPR and, for expatriates, a valid residence permit
- Salary certificate or recent payslips, and usually three to six months of bank statements
- A salary transfer to the lending bank in many cases, though non-salary-transfer options exist at slightly higher rates
- Minimum monthly salary thresholds, which vary by lender and by loan amount
- A debt burden ratio within Central Bank of Bahrain guidelines, generally no more than 50 percent of income committed to loan repayments
Tips for a smarter SUV loan
- Compare total cost, not just the instalment. A slightly higher monthly payment over a shorter term can save a significant sum.
- Keep a buffer. Budget for fuel, insurance renewal and servicing on top of the instalment.
- Ask about early settlement. If a bonus or end-of-service payment is likely, a loan that allows partial settlement without heavy penalties is worth a small premium.
- Time your purchase. Dealer campaigns around Ramadan, National Day and model-year changeovers often include reduced rates or deferred first payments.
Financing a JAC SUV through Khalil Kanoo Motors
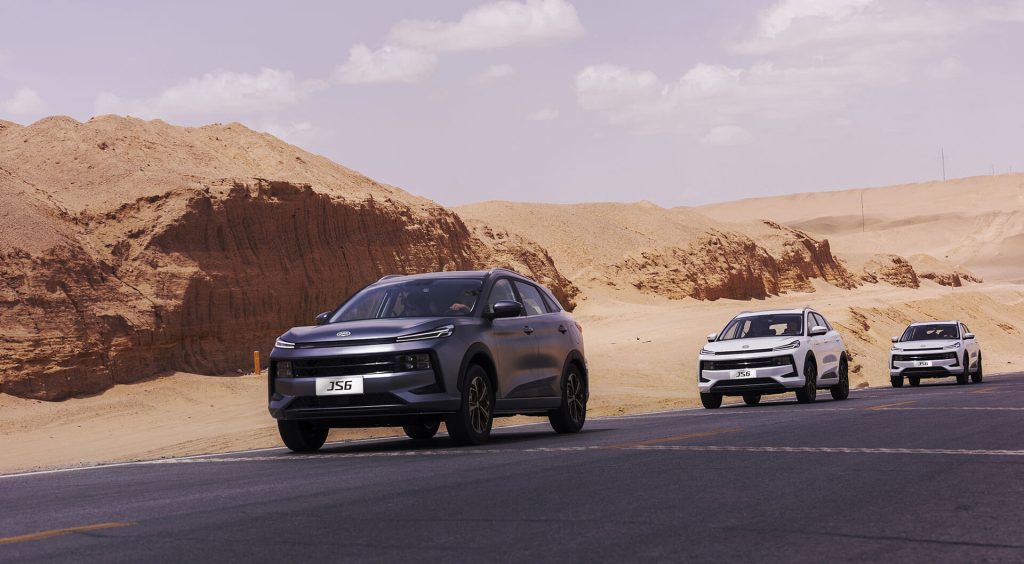
Because Khalil Kanoo Motors has worked with Bahrain’s banks for decades, our sales team can arrange finance for you at the showroom, often with same-week approval. Whether you are looking at the JAC JS4, the larger JAC JS6 or the value-focused JAC S3, we will quote you a clear monthly figure, explain every fee, and handle the paperwork with the bank and the traffic directorate.
Not sure which SUV to finance? Our guides to the compact SUV and crossover segments are a good place to start.
Get a quote
Send a sales enquiry with the model you are interested in and your preferred down payment, and we will come back with financing options. Or book a test drive and talk it through with us in person.
This article is general information, not financial advice. Rates, eligibility and terms are set by the lending institution and change from time to time.